Rare Earth Elements: Is US Reliance on Chinese Imports Coming to an End?
/The clock is ticking on the US-China trade truce as the US government and american mining companies race to supposedly decouple from chinese rare earth element (ree) supply chains. but where will the US turn to for its rees, and how feasible is decoupling by early-2027. SDSG intern Matthew Schwarzenbach tells us it’s not so simple, but SDSG’s new Global inventory of advanced ree assets allows us to understand where the us will likely look both at home and abroad.
By Matthew Schwarzenbach
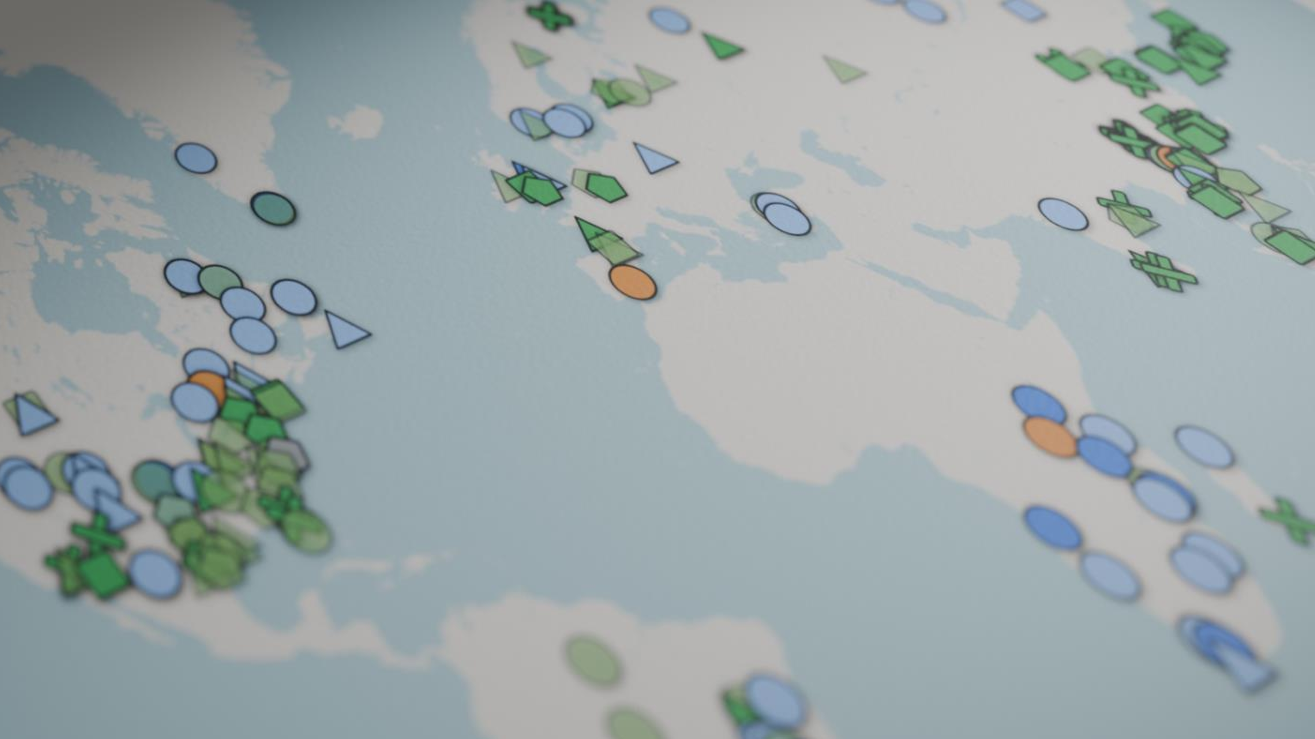
REE Facility Map. https://www.sdsg.org/global-rare-earth-element-inventory
“Rare Earth Elements” (REE) refer to 17 elements on the periodic table which have unique chemical properties that make them critical for a wide variety of uses, including permanent magnets, catalysts, phosphors, ceramics, optics, and medical applications. Due to their widespread use and various applications, the current US administration has taken a keen interest in REEs, seeking to address high levels of supply chain concentration for REE production and processing that takes place in China and through Chinese companies. As of April 2026, Chinese companies own and/or are responsible for nearly 35% of all global commercial production sites for REEs, mining 70% of all REEs and processing over 90% worldwide.
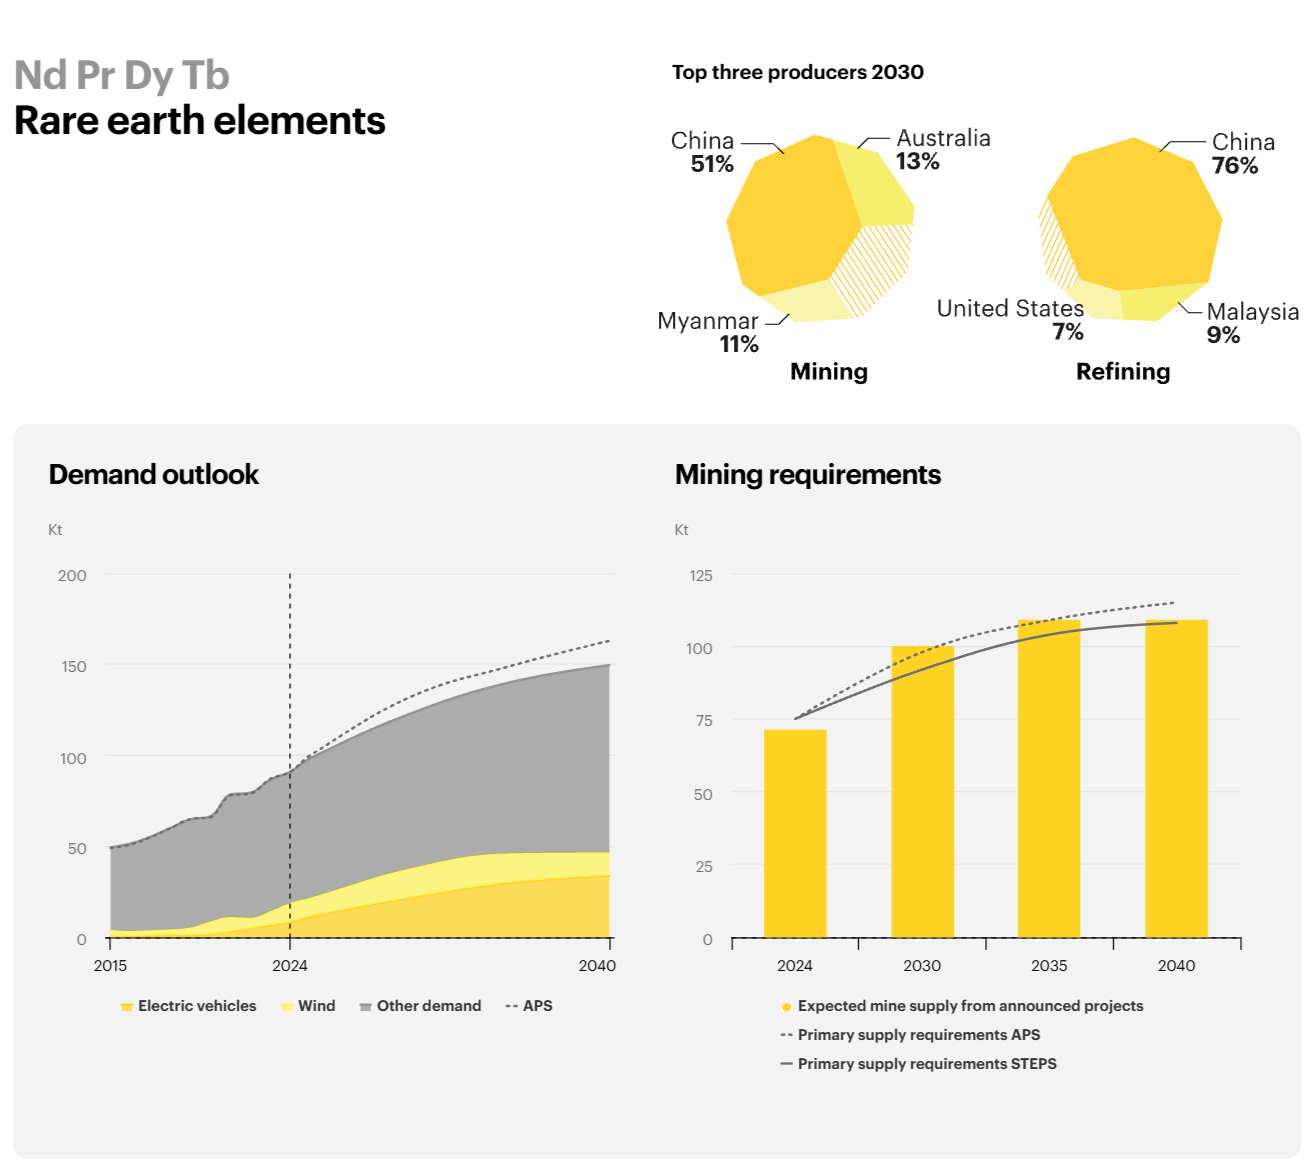
Global REE production and demand projections from IEA in 2025 for Neodymium, Praseodymium, Dysprosium and Terbium - https://www.iea.org/reports/rare-earth-elements-2025
Spurred by the Trump Administration’s onshoring and “friendshoring” policies, US mining corporations and government agencies are increasingly collaborating to “decouple” REE supply chains from Chinese production and processing facilities by January 1st, 2027. After this day, many US-based manufacturers will be prevented from purchasing a number of REEs from China under federal regulations. In an effort to meet this deadline, the current administration has committed tens of billions of dollars across 150 different mining companies, not all for REEs. The largest investment came in January 2026, when the US government committed to inject $1.6bn into a domestic rare earths company, receiving a 10% stake in USA Rare Earth.
From September 23-25, 2026, Chinese president Xi Jinping visited the US to take part in negotiations surrounding US-Chinese trade. During these talks, REEs were a focal point, as President Trump has reportedly refused to extend the current trade truce past January 10th, 2027, on the grounds that China is not fulfilling commitments to export a stable amount of REEs to Western nations, predominantly the US. In fact, Chinese exports of REEs to the US fell 20% from July to August of this year, down a total of 16% from the same time last year despite the trade truce.
Due to the deteriorating confidence in the US-China trade partnership, the US Government has been working furiously to bring online other sources of REE supply and processing. But where precisely are these REE assets located and are they sufficient to meaningfully reduce American supply chain dependence on China?
New Global Inventory Of Rare Earth Mines and Processing Facilities
SDSG’s new open access report and map establishing a Global Inventory of Advanced Rare Earth Element Assets, authored by Andrew Gulley and Graham Lederer, allows users to view all known operating REE assets on a global level as well as mine projects that have reported resources or reserves, mine projects that have already received significant U.S. government funding, and advanced production facilities. The interactive map geolocates all known REE sites and provides more information as to the status and type of each site.
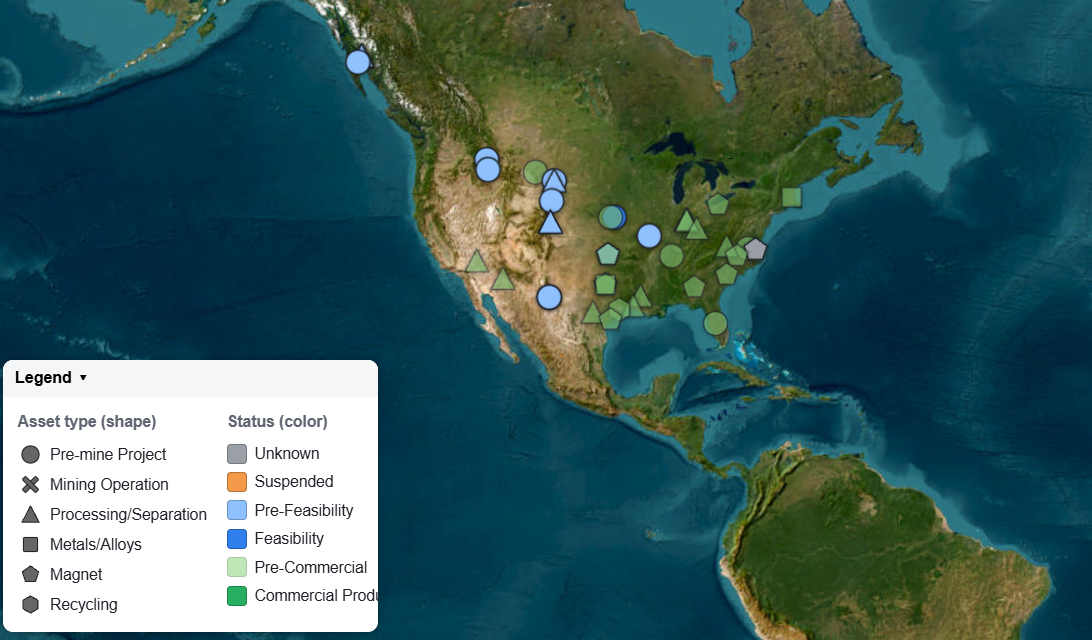
Locations of pre-feasible, feasible, pre-commercial, and unknown REE sites in the US on the interactive map - https://www.sdsg.org/rare-earth-elements-landing-page
As of April 2026, 31 of 89 or nearly 35% of operational REE commercial production sites globally are located in China and only 13% of global sites are in the continental US. Due to recent US government investments and offtake agreements, the US now has more projects in the pipeline than China with nearly 25% of global sites at the pre-feasible, feasible, and pre-commercial phases collectively. But time is a major constraint. While these deposits, mines, and processing facilities can be turned into operating commercial production sites, it can take years or decades to fully develop these sites into reliable sources of REEs.
If the US does completely stop imports of Chinese REEs or if China ramps up export restrictions, the US will have to find these materials elsewhere. Currently, historical US allies such as Japan hold the second most commercial production sites in the world at nearly 15% and Australia and Canada hold a significant share of the world’s mineral deposits, with each country hosting 13% of global pre-feasible, feasible, and pre-commercial sites.
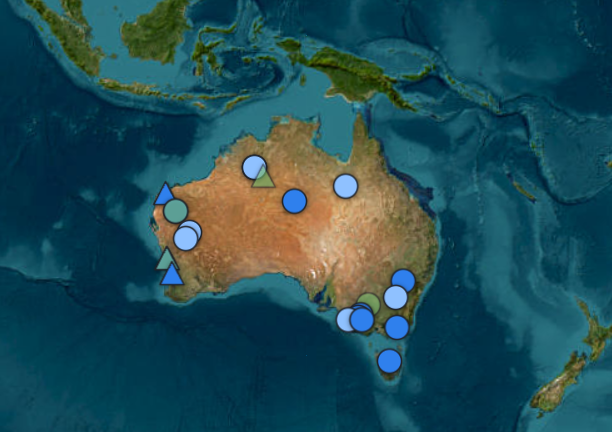
Locations of pre-feasible, feasible, and pre-commercial REE sites in Australia on the interactive map - https://www.sdsg.org/rare-earth-elements-landing-page
Supply and Demand
REEs require an intensive production cycle before they are usable products. The mismatch between the US and China in this sector is the reason why China has been able to maintain its leverage through trade. If the US refuses all future Chinese supply, there will be an even greater mismatch between demand and available supply of these REEs.
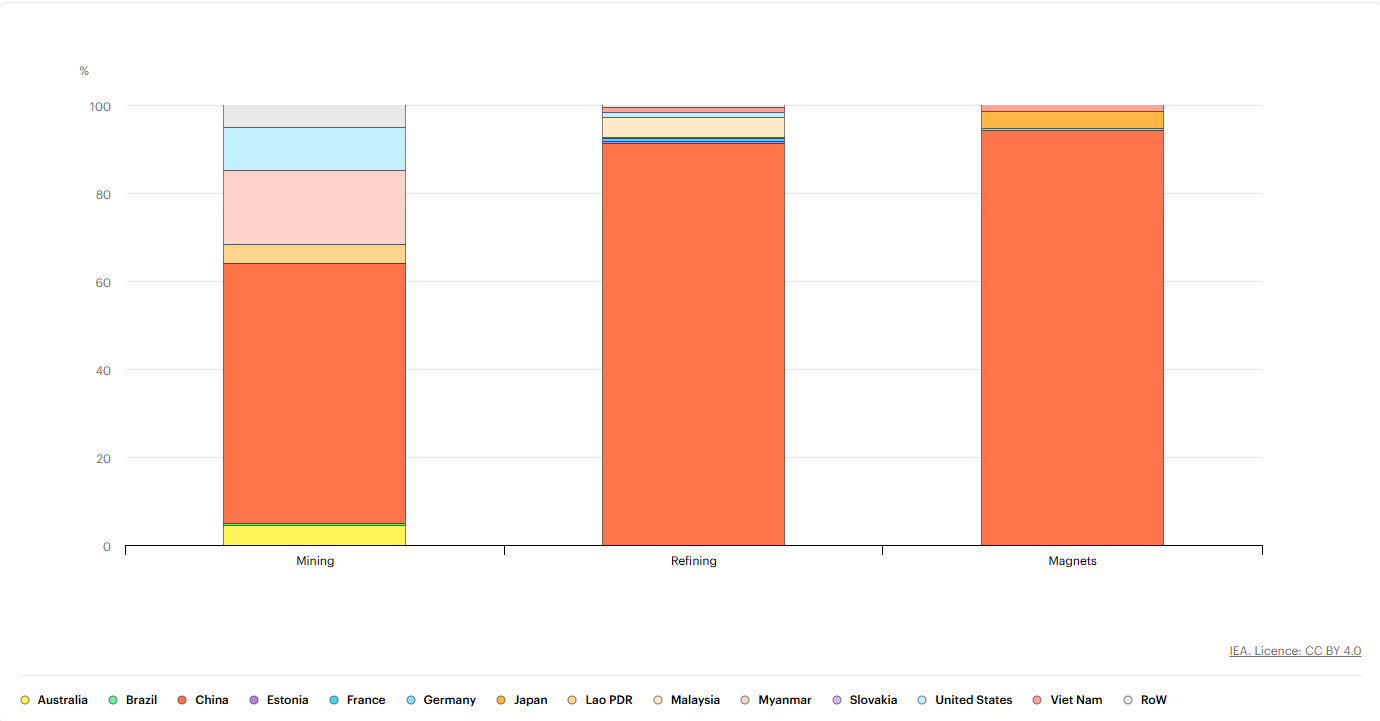
IEA 2026; Share of global supply of magnet rare earths and magnet manufacturing - https://www.iea.org/data-and-statistics/charts/share-of-global-supply-of-magnet-rare-earths-and-magnet-manufacturing-2024, IEA. Licence: CC BY 4.0
In 2025, the most common type of rare earth magnet, the neodymium magnet, had a demand of about 48,000 metric tons while domestic US production could only meet 5,000 metric tons of supply that year. In 2024, Chinese production was responsible for 91% of rare earth magnets. The demand for which is projected to only grow to more than 120 kt in 2030, mainly driven by EV markets. The story is the same with other REEs. According to the USGS, 2025 total US production for all REEs reached 51,000 metric tons while imports numbered 22,450 metric tons, up 169% from 2024. Of these imports, 71% are coming from China, even with current trade restrictions. If US production loses this import avenue, there will be a significant gap that needs to be filled. In the US, there are 6 magnet REE sites in the pre-commercial stage according to our Global Inventory. The cumulative output of these sites is projected to produce up to 17,000 metric tons of magnet REEs a year. Production from these additional sites, on top of imports from friendly nations, would be significant, but still insufficient, to wean the US from Chinese imports.
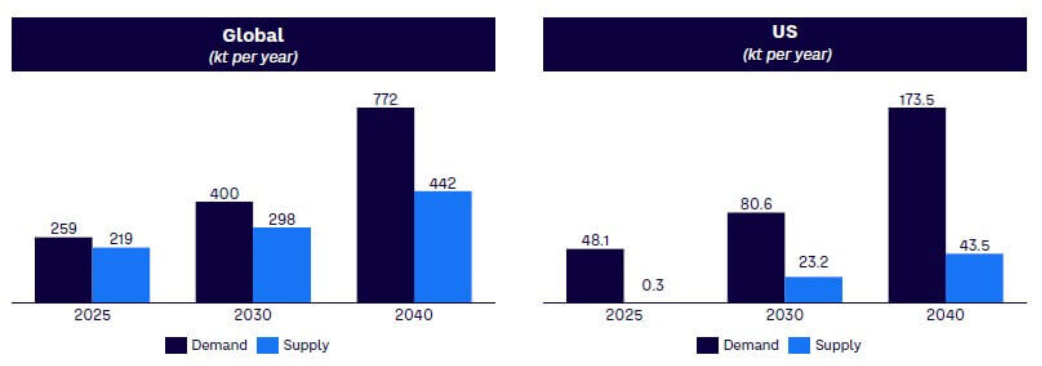
Global and US supply and demand projections for neodymium magnets based on publicly available information in February 2026 - https://www.adlittle.com/en/insights/viewpoints/demand-surging-rare-earth-magnets
Conclusion
Exactly where the United States’ REE procurement will turn next year remains to be seen, but our data from the Global Inventory of Advanced Rare Earth Assets indicates there is a strong chance that in addition to investment in domestic mining and processing, future efforts will focus on Japan, Canada, Malaysia and Australia. Using the Interactive Map we can see that these locations have the most REE sites outside of China and the US.
Given that these measures seem unlikely to meet demand, US reliance on Chinese imports is unlikely to come to an end. There is of course an alternative pathway: partial decoupling from Chinese suppliers and, in parallel, international cooperation on trade and investment with China to unlock REE export controls. In the end it will come down to policy–does Washington have the appetite and agility for strategic collaboration with China, alongside geopolitical competition?